
(415) 717-7243
Your Offer Was Accepted in Novato—What Happens Next?
What happens after a seller accepts your offer on a Novato home?
An accepted offer starts the next stage of your purchase: escrow, property investigations, document review, financing, and preparation for closing. Your signed agreement determines the deadlines and conditions, so your first priority is understanding what needs to happen—and when.
You found a Novato home that fits your needs, submitted an offer, and received the news you were hoping for: the seller accepted.
It is an exciting moment. It is also the beginning of several important decisions.
A showing helped you decide whether the home deserved a closer look. Now you need to evaluate the property more thoroughly, complete your financing, and make sure you understand your contractual obligations before moving forward.
Here is how to approach the process.
1. Review Your Agreement and Calendar
Before focusing on moving boxes or furniture, review the accepted purchase agreement with your agent.
Confirm:
- The earnest-money deposit amount and delivery deadline.
- Which contingencies are included.
- Inspection and investigation deadlines.
- Financing and appraisal timelines, if applicable.
- The scheduled closing date.
- When possession is expected.
- Any negotiated repairs, credits, or other special terms.
Do not assume that every purchase follows the same schedule. The details in your signed agreement matter more than a generic online timeline.
Ask your agent for a written calendar that clearly identifies the tasks you are responsible for and the decisions coming up next.
For an overview of the purchase process, review my Buyer’s Guide.
2. Organize the People Involved
Your agent, lender, escrow officer, title company, inspectors, and insurance professional have different roles. Knowing whom to contact can prevent confusion.
Save their verified contact information early. If you receive unexpected payment instructions or requests to change where funds are sent, stop and independently confirm the instructions with your escrow officer using a previously verified phone number.
3. Read the Property Documents
The disclosure package may contain seller disclosures, inspection reports, natural-hazard information, improvement records, and other property documents. Review them carefully rather than relying only on a summary.
Make a running list of questions:
- What issues or repairs are described?
- Are supporting invoices or reports available?
- Were additions or major improvements documented?
- Are there recurring problems that need further investigation?
- What information is missing or unclear?
Also review the preliminary title report with the appropriate professionals. A title search examines ownership and recorded matters affecting the property, including debts and encumbrances. Ask about any exceptions or recorded documents you do not understand, especially if they could affect access, use, or your plans for the property.insurance.ca
If the home belongs to an HOA, review the available association documents, financial information, insurance, maintenance responsibilities, restrictions, and assessment information. Seek qualified legal or financial advice when needed.
4. Investigate the Home’s Condition
An accepted offer does not resolve every question about the property. Use the investigation period provided by your agreement to review available reports and arrange any appropriate inspections or specialist evaluations.
Depending on the home, you may want to discuss:
- General home and pest inspections.
- Sewer lateral condition.
- Roofing, electrical, plumbing, or structural concerns.
- Pool equipment and condition.
- Drainage or other property-specific issues.
Ask inspectors to distinguish between immediate concerns, routine maintenance, and items that warrant another professional’s evaluation. A finding is not automatically a reason to cancel—but it should be understood before you make a contractual decision.
If concerns arise, your agent can help you discuss possible next steps. Negotiating repairs, credits, or changes is not guaranteed; the seller’s response and your options depend on the agreement and circumstances.
5. Keep Financing Moving
If you are financing the purchase, stay in close contact with your lender. Ask what documents remain outstanding and whether any approval conditions could affect the closing date.
Discuss proposed financial changes with your lender before making them. A new loan, large purchase, job change, or unusual transfer of funds may require further review.
Understand the appraisal’s role
An appraisal is an opinion of the home’s market value used in the lending process. It is different from a condition inspection and does not replace one.nar
If the appraised value is below the purchase price, ask your lender how that affects your financing. Then review your contractual options with your agent. Possible responses may include further negotiation or additional buyer funds, but the available choices depend on your loan, agreement, and circumstances.nar
6. Resolve Insurance and Ownership-Cost Questions
Do not leave unresolved insurance questions until the final days before closing. Confirm with your insurance professional and lender:
- Whether the required coverage is available.
- The premium and deductible.
- Any exclusions or additional coverage to consider.
- Whether the insurer requires changes to the property.
- When coverage needs to take effect.
Also finish reviewing costs that are separate from the loan payment, such as HOA dues, utilities, maintenance, pool service, and any solar obligations.
For a Novato home with solar, ask about ownership, financing or lease terms, transfer requirements, and applicable billing information. The purpose is to understand the obligations you are taking on—not simply whether the home has solar panels.
7. Make Contingency Decisions Deliberately
A contingency is a negotiated condition in your purchase agreement. Depending on what you agreed to, contingencies may relate to financing, appraisal, inspections, document review, or other matters.
Before making a decision about removing one, ask:
- Have I received and reviewed the relevant information?
- Are important questions still unanswered?
- Do I understand the findings and potential costs?
- Has my lender confirmed the status of financing?
- What does removal mean under my agreement?
- What happens if I need more time?
Do not treat contingency paperwork as a routine administrative step. Have your agent explain the process, and seek legal advice if you do not understand your rights or potential exposure.
8. Review Your Closing Disclosure
For most mortgages, your lender must provide a Closing Disclosure at least three business days before closing. It details the loan terms, projected monthly payments, and closing costs so you can compare them with your earlier Loan Estimate.consumerfinance
Review:
- Loan amount, interest rate, and payment.
- Whether the rate is fixed or adjustable.
- Taxes, insurance, and escrow-account information.
- Lender charges and other closing costs.
- Seller and lender credits.
- Funds you have already paid.
- The remaining cash needed to close.
Ask about discrepancies before signing. The review period is there to give you time to understand the transaction—not merely acknowledge receipt of a document.consumerfinance
9. Complete the Final Walk-Through
Before closing, use the final walk-through to check the property against what was agreed.
Confirm that:
- Agreed repairs have been completed.
- Items the seller agreed to leave are present.
- The property’s condition is consistent with the agreement.
- Any new concerns are raised promptly.
The Consumer Financial Protection Bureau recommends a final walk-through before signing closing papers to verify agreed repairs and included items. Report problems immediately rather than assuming they will be resolved afterward.consumerfinance
10. Confirm Closing and Possession
Signing documents, lender funding, recording, and receiving the keys are related steps, but they are not necessarily the same event.
Ask your agent and escrow officer to explain what remains outstanding and when you can take possession under the agreement. Coordinate movers, utility service, and access around confirmed arrangements—not an assumed handover time.
If the seller will remain after closing, make sure the applicable occupancy terms are clearly documented and understood.
Frequently Asked Questions
How long does escrow take for a Novato home?
There is no single timeline for every purchase. Your agreement sets the planned closing date, while financing, investigations, document review, and other transaction requirements can affect whether that date is met.
Does an appraisal replace a home inspection?
No. An appraisal addresses market value for the lending process. It is not a substitute for investigating the property’s condition.nar
Can I ask for repairs after inspections?
You can discuss a request with your agent, but acceptance is not guaranteed. Your rights, deadlines, and options depend on the purchase agreement and the circumstances.
When should I review the final mortgage costs?
Review the Closing Disclosure as soon as you receive it. For most mortgages, you must receive it at least three business days before closing, giving you time to compare it with the Loan Estimate and ask questions.consumerfinance
Bottom Line
An accepted offer is an important milestone—not the end of the evaluation process. Stay organized, meet your deadlines, ask questions, and make sure you understand the property, financing, and agreement before moving forward.
If you are planning to buy in Novato, contact me to discuss your search and how to prepare for the steps between an accepted offer and closing.
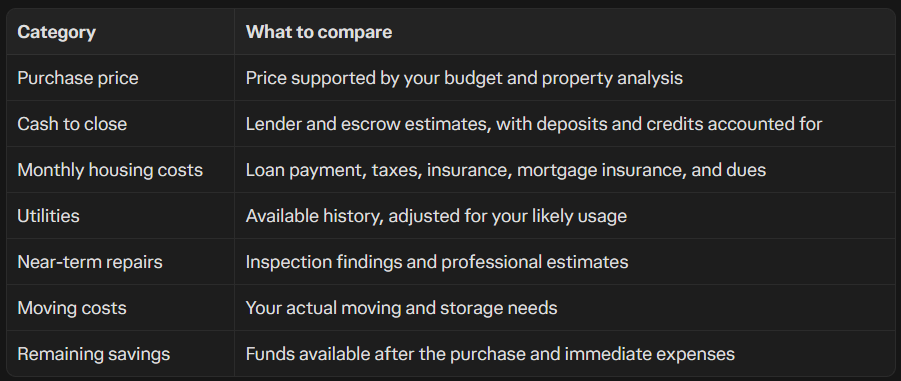
Buying a home in Petaluma? Plan for closing costs, insurance, taxes, inspections, utilities, and repairs—not just your down payment and mortgage.
What should you check when touring a home in Novato?
Can You Buy Your Next Petaluma Home Before Selling Your Current One?
Getting ready to sell your Novato home? Follow this practical timeline for repairs, staging, disclosures, pricing, photos, and showings before you list.
Compare real estate agents in Petaluma and Novato beyond star ratings. Learn how to assess reviews, sales results, local expertise, strategy, and fees.
Compare real estate agents in Petaluma and Novato with this buyer and seller guide. Evaluate local experience, marketing, negotiations, reviews, fees, and strategy.
Mortgage rates may change, but you can still influence your loan terms. Learn how credit, loan options, lender comparisons, and buyer incentives can affect your mortgage rate.
Use this step-by-step checklist to choose a Novato real estate agent. Compare local experience, strategy, communication, reviews, fees, and contracts before you buy or sell.
Best Real Estate Agent in Petaluma & Novato: How to Choose the Right Local Expert for Your Next Move
Learn how to choose the best real estate agent in Petaluma or Novato. Compare local expertise, reviews, strategy, communication, negotiations, and fees before you hire.
Learn how to choose the best real estate agent in Petaluma or Novato. Compare local experience, reviews, strategy, communication, fees, and recent results before you hire.