
(415) 717-7243
The Credit Score Myth That Could Be Delaying Your Home Search
What if the number keeping you from buying a home isn't actually the obstacle you think it is?
For many aspiring homeowners, credit scores can feel like the ultimate deciding factor.
You might have a steady job, savings set aside, and a pretty clear idea of the kind of home you'd love to own. Maybe you've even spent a few evenings browsing properties in Petaluma or Novato, imagining what life could look like in a place of your own.
But then you check your credit score.
And suddenly, you start wondering whether homeownership is even possible.
Here's something worth knowing: There isn't one universal credit score required to buy a home. And some important credit-scoring rules have recently changed.
If you've been putting your plans on hold because of a number you saw in a banking app, it may be time to look at the bigger picture.
The Number Everyone Thinks They Need
Ask someone what credit score they need to qualify for a mortgage, and you'll probably hear a confident answer.
Maybe 700. Maybe 660. Maybe even higher.
But confidence doesn't always mean accuracy.
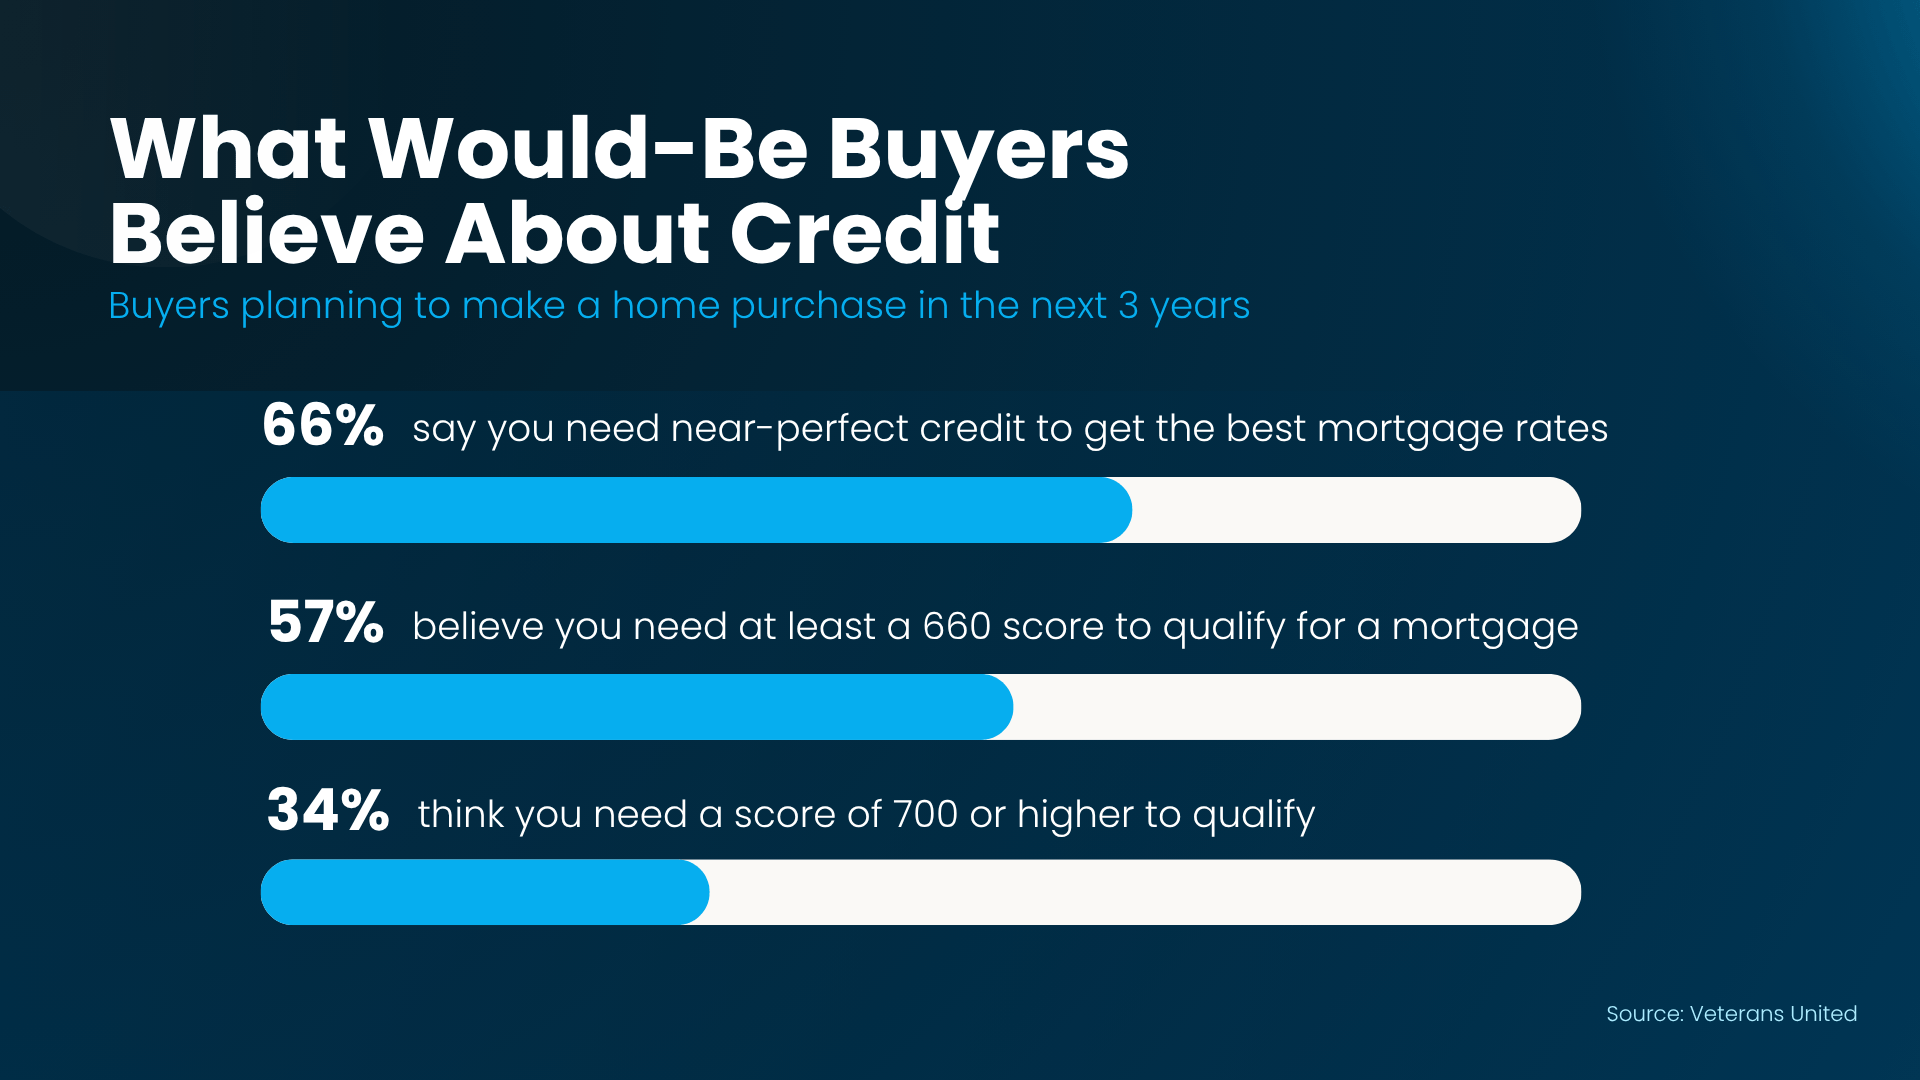
A 2026 survey from Veterans United Home Loans found that many prospective buyers misunderstand mortgage credit requirements.
Among its findings, 34% of respondents believed a credit score of at least 700 was necessary to qualify for a mortgage. More than half believed they needed a score in the mid-600s or higher.
The survey also found widespread misconceptions about the relationship between credit scores and mortgage pricing.
Here's why that matters.
When someone assumes their credit isn't good enough, they may never speak with a lender or explore the programs they could potentially qualify for.
They end up making a major financial decision based on an assumption rather than an actual evaluation.
And in a market like Petaluma or Novato, where buying a home often requires careful planning, understanding your options early can make a meaningful difference.
That doesn't mean everyone with a lower credit score will qualify.
It means your credit score shouldn't be the only piece of information you use to decide whether homeownership is possible.
One of the Biggest Credit Requirements Has Changed
For years, the number 620 was widely associated with conventional mortgage eligibility.
It was often presented as the minimum credit score needed to qualify for loans backed by Fannie Mae.
But in November 2025, Fannie Mae made an important change.
The organization removed its fixed minimum third-party credit-score requirement for applications evaluated through its automated underwriting system, known as Desktop Underwriter.
Instead of using a single minimum score as an entry requirement, Desktop Underwriter evaluates a broader set of credit and financial risk factors.
This includes information about a borrower's credit history and other aspects of their financial profile.
It's a meaningful shift because it recognizes something that should be obvious: a person's financial situation can't always be summarized by one number.
Does that mean you can buy a home with any credit score?
No.
The change doesn't eliminate underwriting standards, guarantee approval, or apply to every mortgage program. Manually underwritten loans and individual lenders may still have specific requirements.
But it does challenge the idea that everyone must meet the same universal score to become a homeowner.
You can read more about this development through Fannie Mae's official Desktop Underwriter credit assessment update.
Your Credit Score May Not Be the Same Number Your Lender Sees
Here's another detail that can surprise buyers.
You don't necessarily have just one credit score.
Different companies use different scoring models, and those models may produce different results from the same underlying credit history.
So the number you see when you log into your credit card account might not be identical to the one a mortgage lender uses.
And the mortgage industry is now expanding the scoring models available to lenders.
In September 2026, Fannie Mae and Freddie Mac expanded the use of VantageScore 4.0, allowing all approved lenders to use it for eligible mortgage loans delivered to those organizations.
For now, lenders can continue using the traditional Classic FICO model or choose VantageScore 4.0 for eligible loans.
Another model, FICO Score 10T, has also been approved for future use, but it isn't yet available for those loan deliveries.
The newer models can consider credit information differently, including patterns in how someone manages their accounts over time.
This doesn't mean every buyer will see a higher score or receive a different approval decision.
It simply means the way mortgage lenders evaluate credit is evolving.
For someone preparing to buy a home, that's another reason not to rely exclusively on a score from a consumer app.
A qualified mortgage professional can help explain which scoring information and underwriting requirements apply to the loan programs you're considering.
Good Credit Habits Still Matter
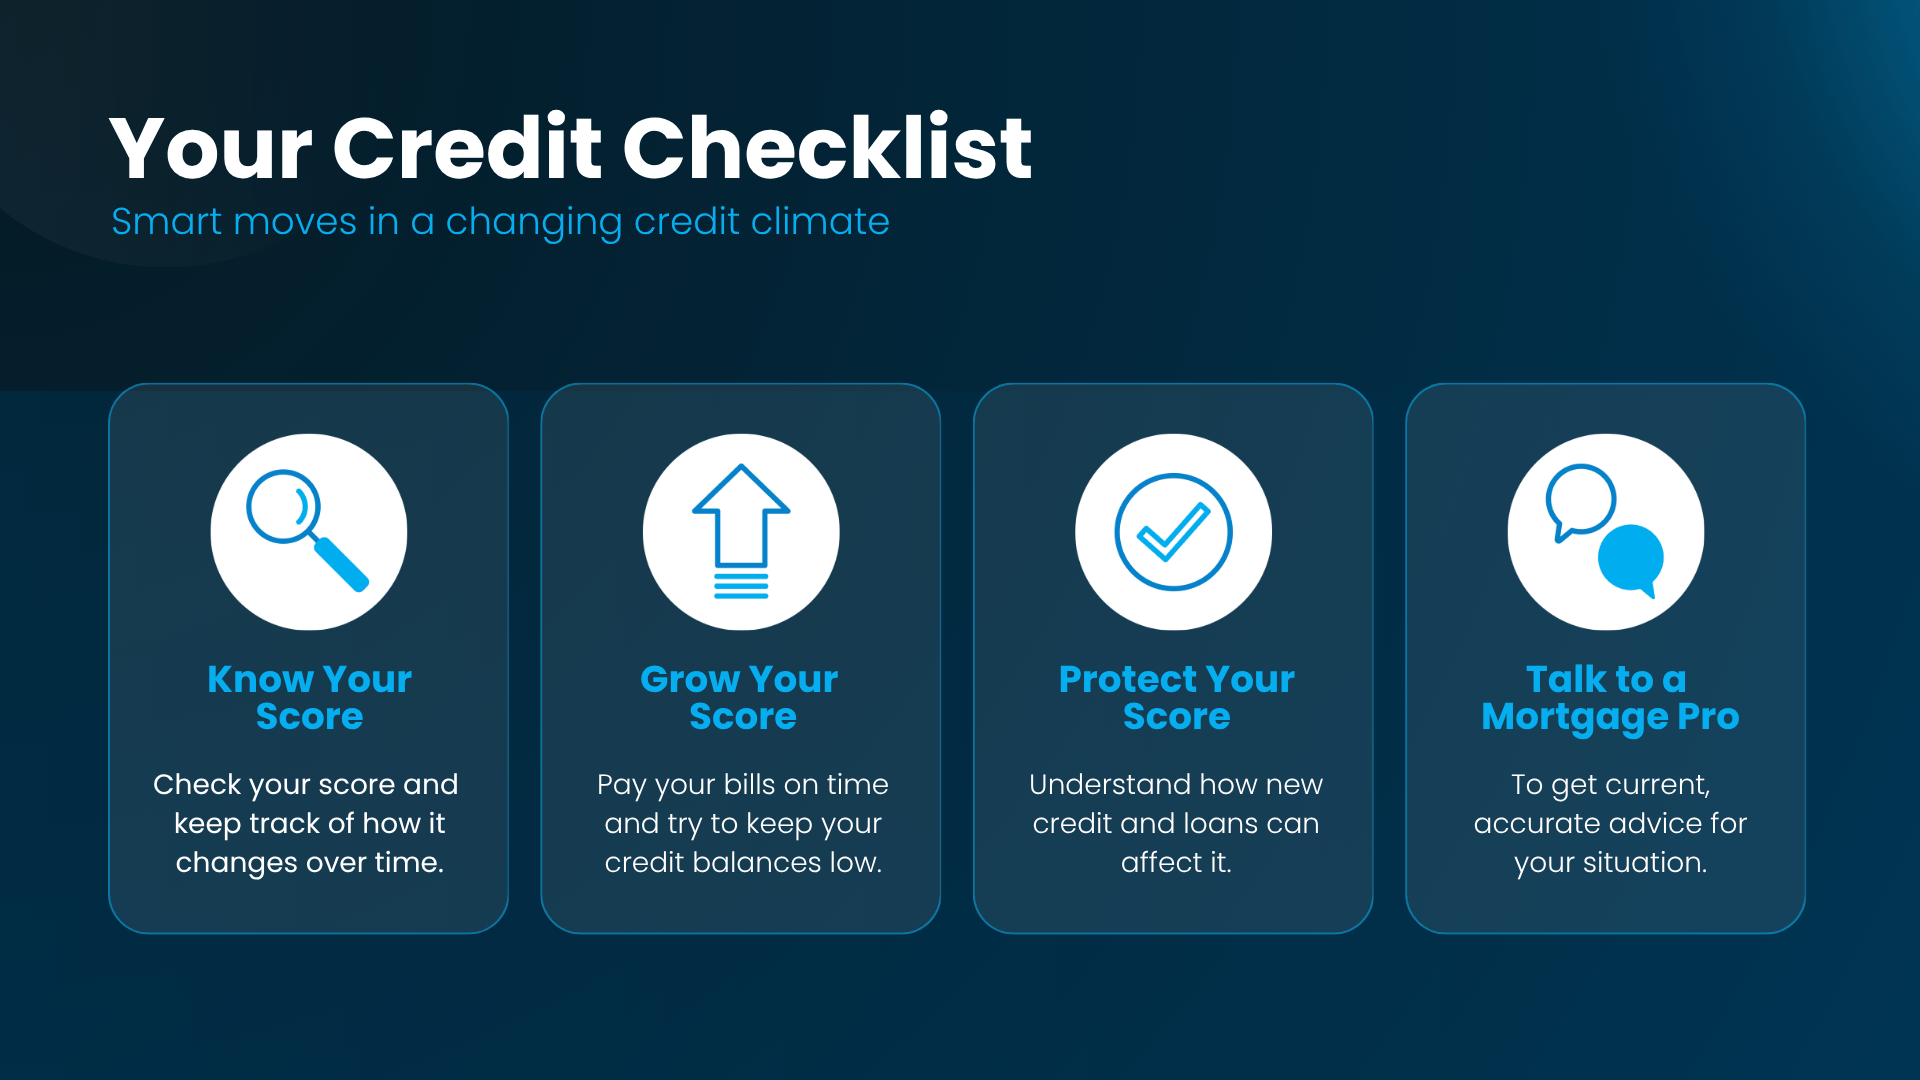
Even as scoring models change, the fundamentals of managing credit responsibly remain important.
Paying bills on time, keeping revolving credit balances manageable, reviewing credit reports for inaccuracies, and understanding how new credit accounts affect your financial profile can all help you prepare.
And you don't have to wait until you've found your dream home to start.
You can begin by reviewing your credit reports through AnnualCreditReport.com, the official website for requesting reports from the three major credit reporting agencies.
Checking your own credit report doesn't lower your credit score.
If you find incorrect information, you can investigate the appropriate dispute process.
The important thing is to understand where you stand today instead of waiting for a number you believe you must reach.
Whether you're planning to buy this year or sometime in the future, building healthy financial habits and getting accurate professional guidance can help you prepare for the next step.
The Compass and Rocket Mortgage Partnership: Another Resource for Buyers
There is also another option worth knowing about if you're considering buying a home with a Compass agent.
Compass has partnered with Rocket Mortgage to provide eligible clients with additional financing resources and potential incentives through its Rocket Preferred Pricing program.
One feature that may be especially helpful is the opportunity to explore preapproval through Rocket's advertised no-credit-impact initial process, giving buyers a way to begin understanding their purchasing possibilities.
The partnership is also designed to support communication between a buyer's Compass agent and Rocket Mortgage loan professional throughout the homebuying process.
For eligible buyers, the program currently offers a choice of promotional financing benefits.
One option for qualifying conforming purchase loans is a lender-paid closing-cost credit equal to 0.75% of the loan amount, up to $6,000.
Other promotional financing options are available, but they cannot be combined with that closing-cost credit. Certain specialized loan products have different eligibility and incentive terms.
The important distinction is that this partnership is an additional resource, not a guarantee of financing or a requirement.
You are never obligated to use Rocket Mortgage simply because you're working with a Compass agent.
Every buyer has the freedom to compare lenders and choose the financing option that best fits their circumstances.
As a Compass Realtor, I can help buyers learn about the resources available through the partnership while encouraging them to compare their options and speak directly with qualified lending professionals.
You can explore the official Compass and Rocket Mortgage partnership for program details.
Program disclosure: Rocket Mortgage financing and promotional benefits are subject to underwriting, eligibility, loan type, and applicable program terms. Offers may change and cannot be combined with other Rocket discounts. The advertised closing-cost credit is available only on eligible transactions. This is not a commitment to lend.
What This Means for Your Home Search
Let's bring this back to the bigger picture.
Maybe you've been considering a home in Petaluma because you love the downtown atmosphere, established neighborhoods, and connection to Sonoma County's surrounding communities.
Or perhaps Novato appeals to you because of its Marin County location, outdoor spaces, and variety of residential neighborhoods.
Wherever you're hoping to settle, your home search doesn't have to begin with finding a listing.
It can begin with understanding your financial position and the options that may be available.
That might mean reviewing your credit history, speaking with a licensed lender, learning about different loan programs, or creating a realistic plan for when you're ready to purchase.
And once you understand those details, you can begin exploring properties with more confidence and clearer expectations.
My role as your real estate professional is to help you understand the local market, find properties that fit your goals, and guide you through the buying process.
You can also explore my Home Buyer's Guide for additional information about purchasing a home in Sonoma and Marin Counties.
Don't Let an Assumption Make the Decision for You
Credit scores matter.
But they're not the only factor lenders consider, and the rules surrounding how they're evaluated are evolving.
The bigger takeaway isn't that everyone can qualify for a mortgage regardless of their financial situation.
It's that you deserve accurate information about your options before deciding that buying a home isn't possible.
Sometimes, a conversation with the right professional can help you understand opportunities or obstacles that a credit-score app simply cannot explain.
And whether you're ready to buy soon or just beginning to explore the idea, there's value in knowing where you actually stand.
Thinking about buying a home in Petaluma, Novato, or the surrounding Sonoma and Marin County communities?
I'd love to help you take the next step, understand your local housing options, and connect with financing professionals who can provide guidance based on your individual circumstances.
Your homebuying journey might have more possibilities than you realize.
Katia Bidaurreta | Realtor® – Compass
CA DRE #02152439
Phone: (415) 717-7243
Email:
katia.bidaurreta@compass.com
Website:
www.katiabidaurreta.com
Contact Katia
Selling a home in Petaluma or Novato? Learn how mortgage payoffs, closing costs, and local transfer taxes affect your seller net proceeds.
Will the silver tsunami flood the housing market? Discover what 13.9 million projected home transitions mean for sellers and future home inventory.
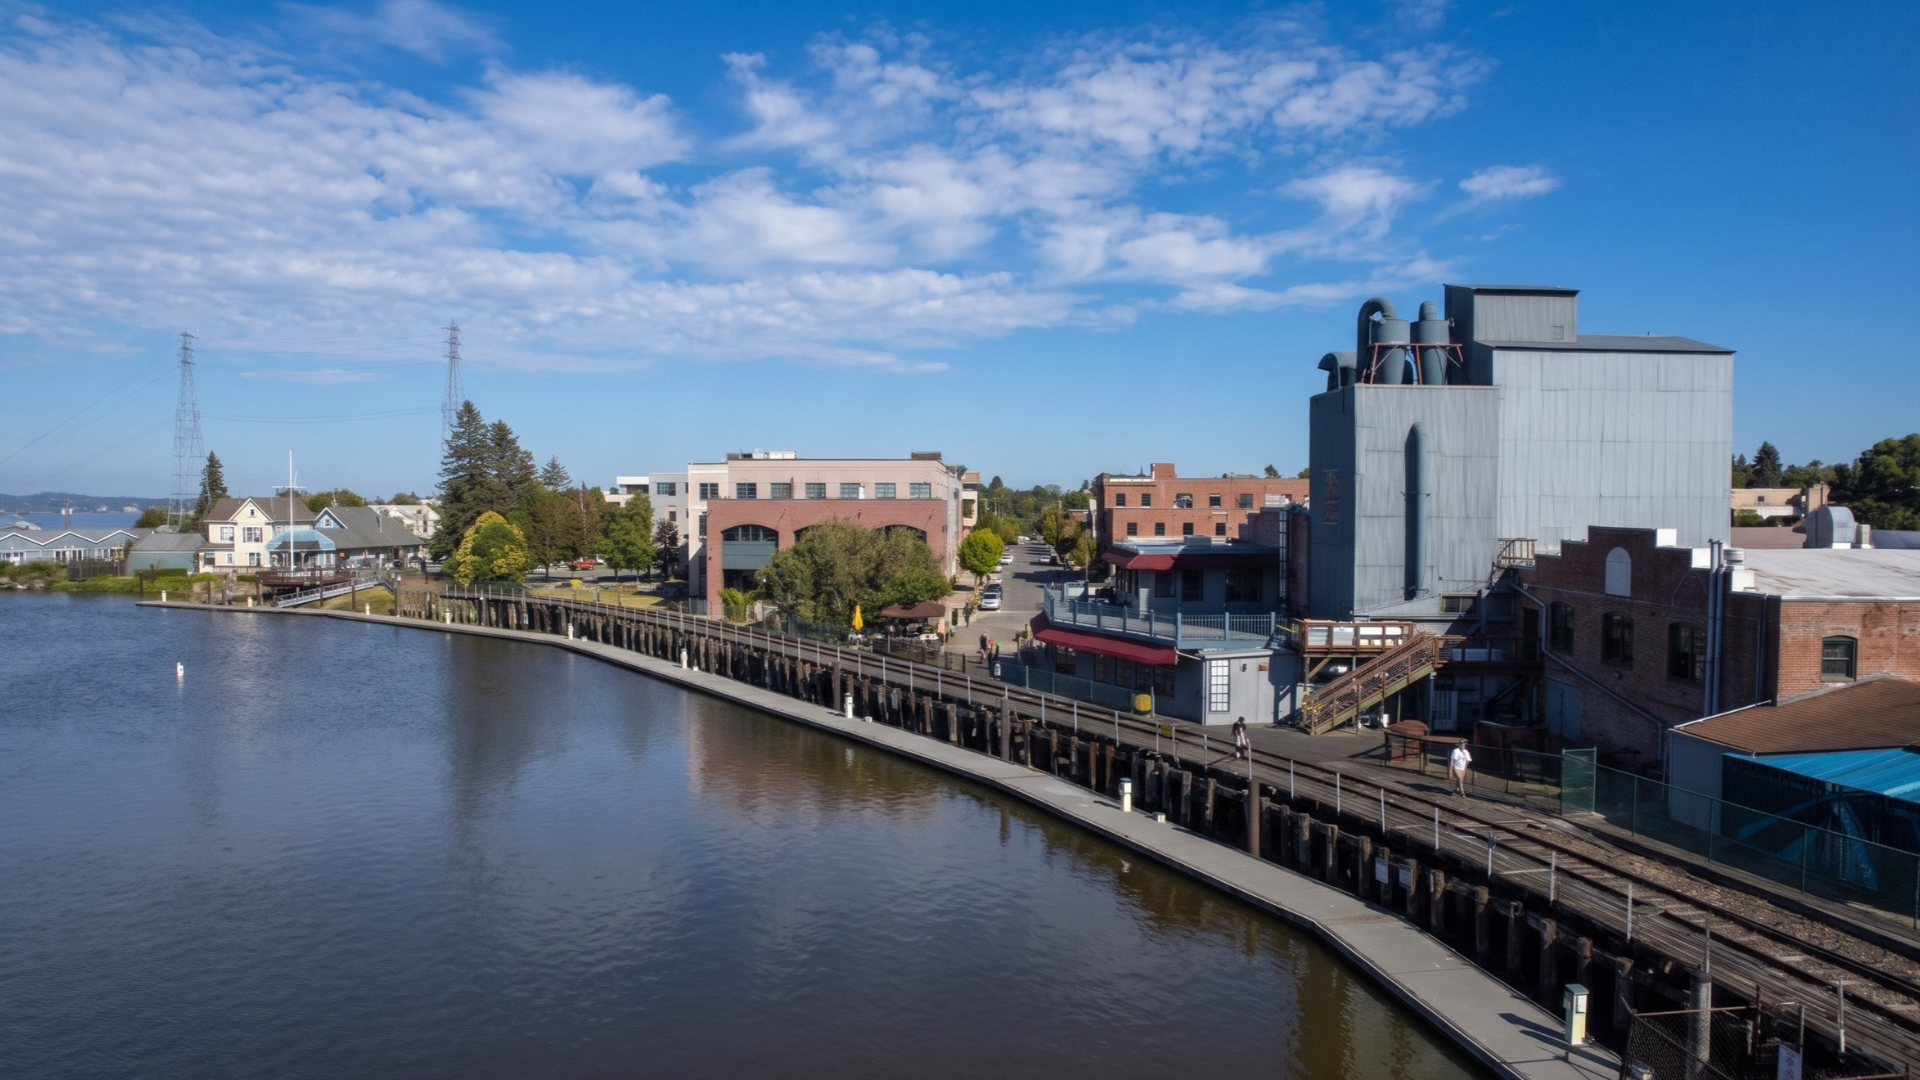
Petaluma's historic railroad trestle could become a public waterfront promenade. Explore the project's history, community progress, and future plans.
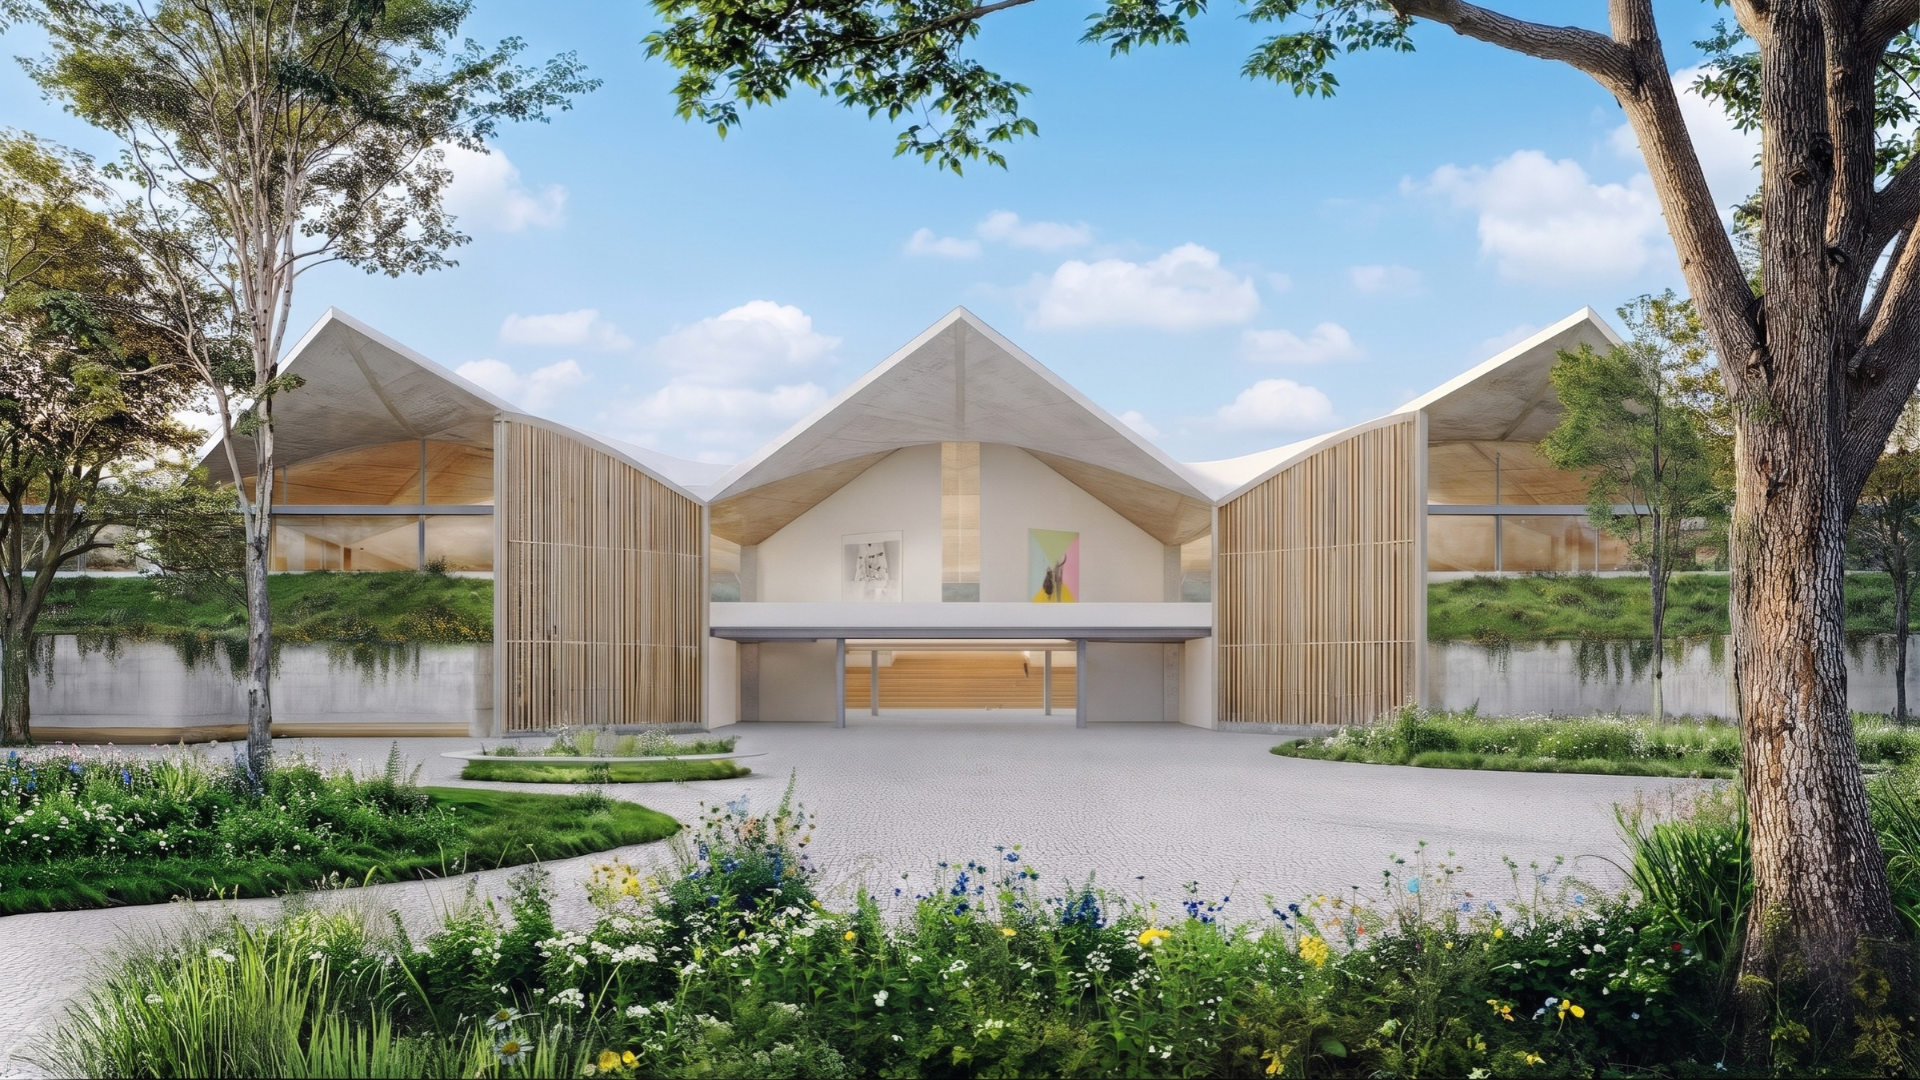
A major design museum is planned for Novato's former Birkenstock campus. Discover its proposed transformation and surprising connection to Petaluma.
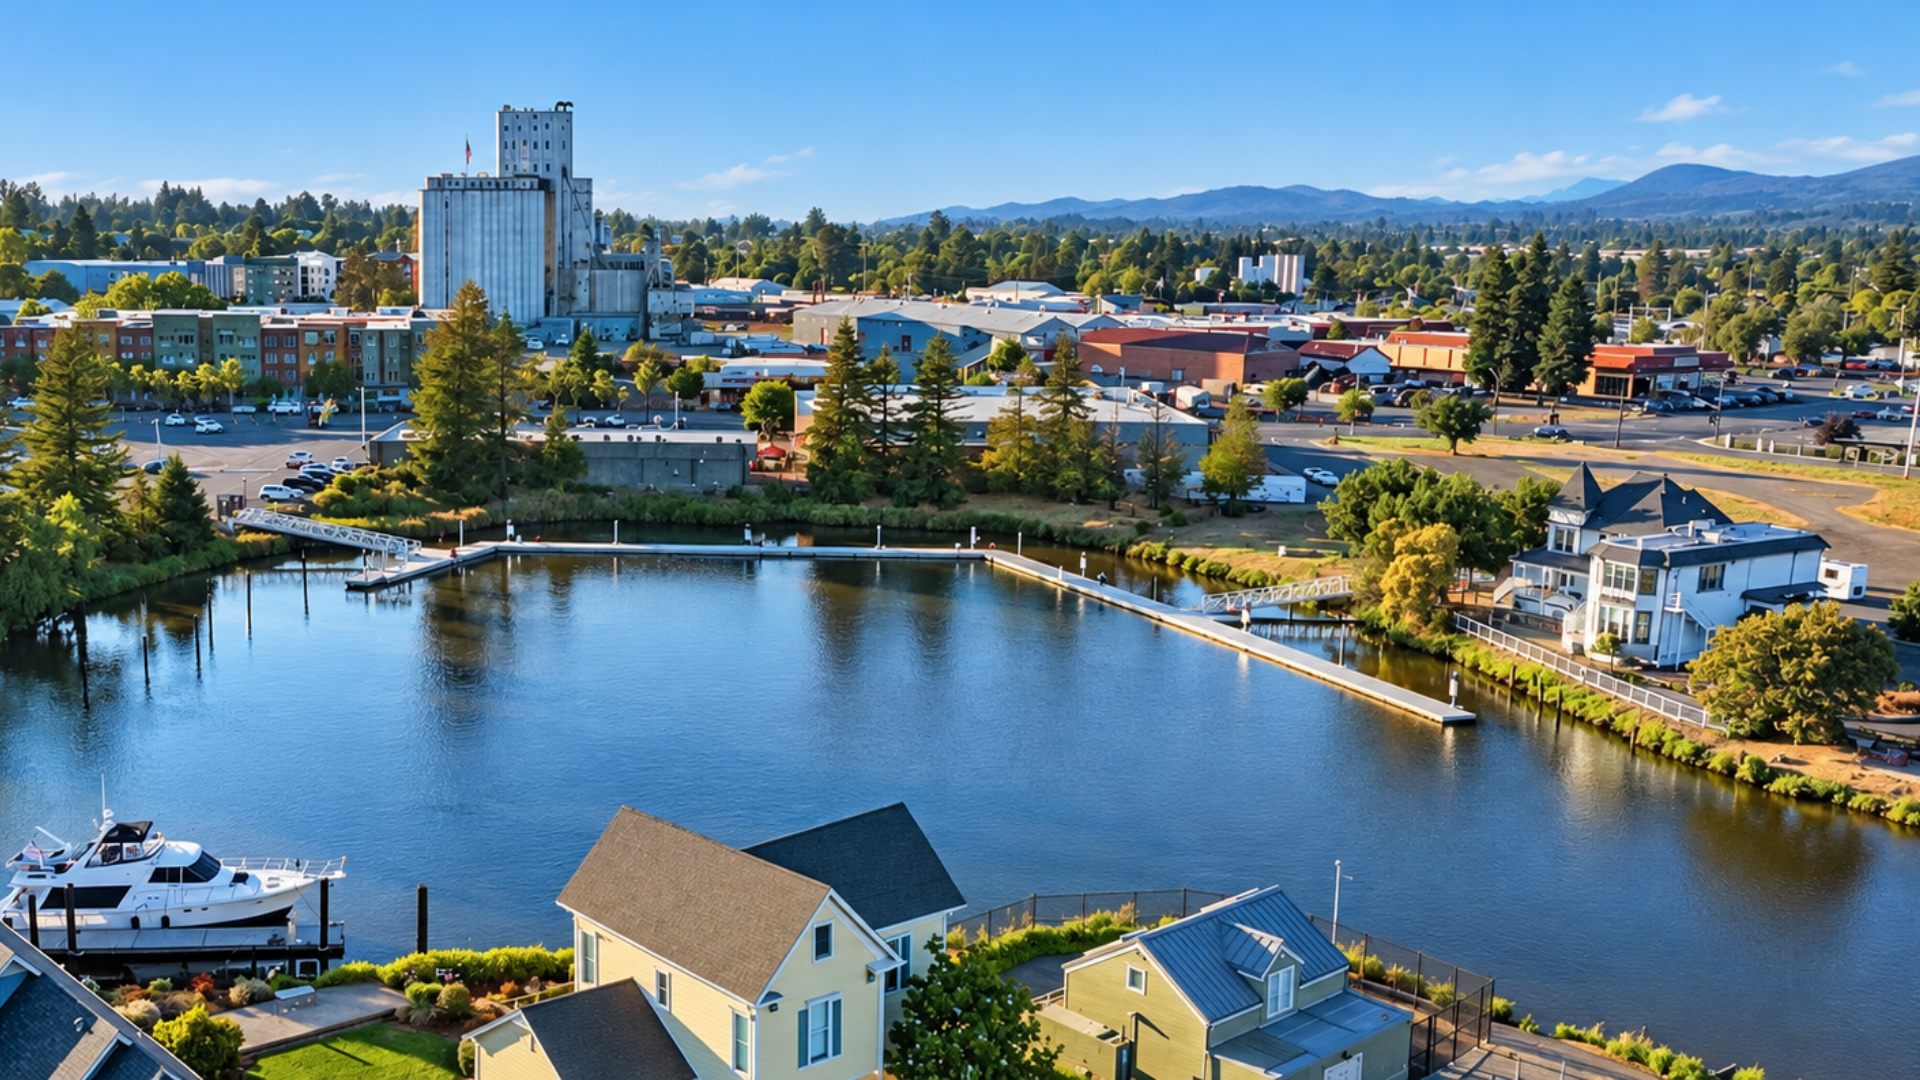
Petaluma's General Plan 2050 is now in effect. Explore what it means for future housing, neighborhoods, downtown, transportation, and local real estate.
By Katia Bidaurreta | Realtor® – Compass
Buying a home in Petaluma or Novato? Discover 5 important checks covering insurance, wildfire hazards, home condition, and local preparedness.
Should you sell or rent your home in Petaluma or Novato? Compare costs, landlord responsibilities, and local market considerations before deciding.
Buying in Petaluma or Novato? Learn how mortgage rate locks work, what to ask about fees and extensions, and how to coordinate your lock with closing.
A price cut does not always mean a bargain. Learn how Petaluma and Novato buyers can compare value, condition, competing listings, and offer terms.